Retail, office, and industrial all offer fundamentally different return profiles, risk characteristics, and management demands. The right answer depends on your goals, your capital, and your appetite for complexity. Here is how the three major commercial asset classes stack up for Triangle investors in 2026.
Jon Tennant
Real Estate & Business Brokerage
~9 min read
One of the most common questions commercial real estate investors ask when they start looking at the Triangle market is which asset class to focus on. Retail, office, and industrial all offer fundamentally different return profiles, risk characteristics, and management demands. The right answer depends on your goals, your capital, and your appetite for complexity. Here is how the three major commercial asset classes stack up for Triangle investors in 2026.
Retail commercial real estate covers everything from a single-tenant fast food pad to a 50,000 square foot neighborhood shopping center. What unites the category is that retail tenants depend on consumer foot traffic and spending — which means location is the dominant value driver, and tenant quality determines income stability.
The Triangle retail market has been more resilient than many markets nationally. Strong population growth, rising household incomes, and a continued influx of new residents have kept retail demand healthy in well-located trade areas. Vacancy for the Triangle retail market runs approximately 6-7% in 2026, which is manageable and in line with a healthy market.
The best performing retail in the Triangle right now is necessity-based and service-oriented. Grocery-anchored centers, medical retail, fitness, personal services, and food and beverage in strong suburban trade areas are performing well. Discretionary retail in weaker trade areas or with credit-challenged tenants is more fragile.
For investors, retail's attraction is income — well-structured triple net leases with creditworthy tenants generate consistent cash flow with minimal landlord management responsibility. The risk is tenant rollover. When a retail tenant vacates, re-leasing takes time, requires landlord investment in tenant improvements, and may happen at a different rent than the prior tenant was paying.
Cap rates for stabilized Triangle retail in good locations run approximately 6.0-7.5% in 2026. Single-tenant NNN properties with national credit tenants (fast food, pharmacy, dollar stores) trade at tighter cap rates in the 5.0-6.5% range because investors pay a premium for the income certainty.
Office has been the most challenged commercial asset class since 2020, and the Triangle is no exception — though it has fared better than most markets. Remote and hybrid work permanently reduced demand from many traditional office users, and lease expirations have added vacancy in submarkets across the metro.
As covered in detail in our office trends post, the Triangle office market is bifurcated. Medical office, suburban Class A in strong locations, and flex office are performing. Older Class B and C product and downtown large-block space face meaningful headwinds.
For investors, office requires more selectivity than it did five years ago. The days of buying any occupied office building at a reasonable cap rate and holding it passively are over. You need to underwrite tenant quality, lease term, realistic re-leasing assumptions, and capital expenditure requirements with much more discipline. The upside case for office in 2026 is value-add repositioning — buying older or partially vacant product at a price that reflects the challenges, investing in improvements, and re-leasing to a stronger tenant base. This requires more hands-on management and more capital, but the spread between the acquisition cap rate and the stabilized value can be significant if executed well.
Cap rates for stabilized Triangle office run approximately 7.0-8.5% in 2026 for suburban product, with higher cap rates (reflecting higher risk) for challenged assets or locations.
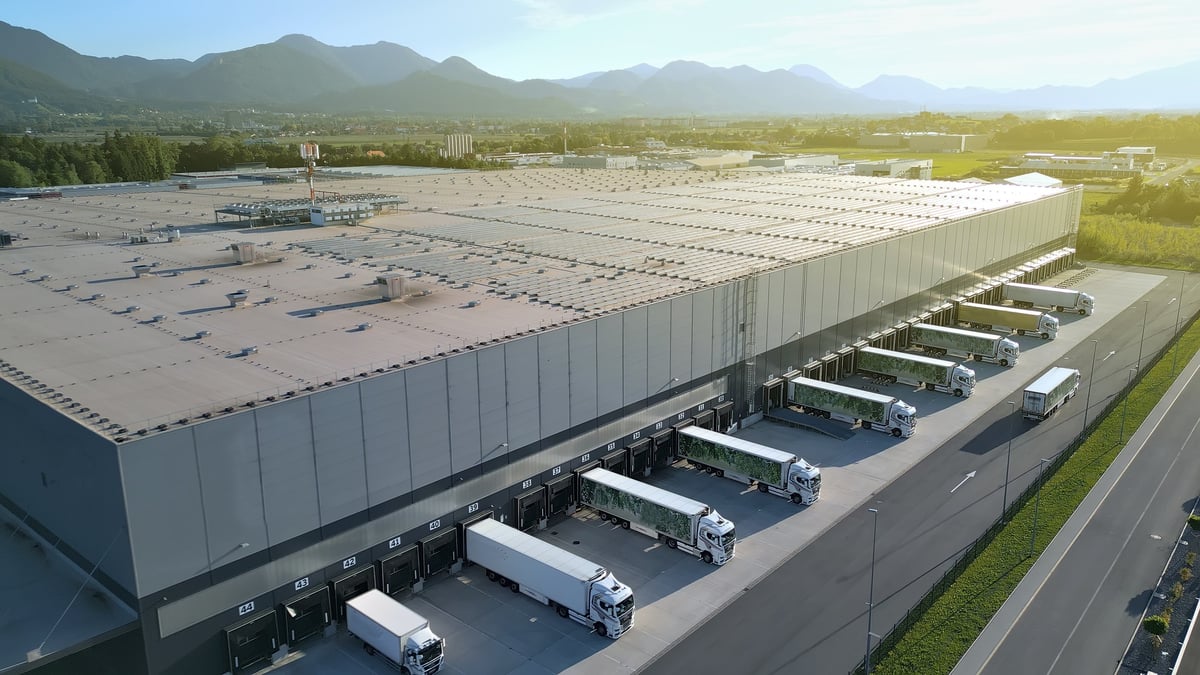
Industrial and flex space has been the standout commercial asset class in the Triangle and nationally for the past several years. E-commerce growth, supply chain restructuring, life sciences expansion, and logistics demand have driven occupancy and rents higher while keeping vacancy near historic lows.
The Triangle's position as a life sciences and biotech hub, combined with its role as a regional distribution center and its access to I-40, I-85, I-540, and RDU Airport, creates structural demand for industrial and flex product that shows no sign of slowing. Amazon, FedEx, UPS, and dozens of smaller logistics and manufacturing operations compete for quality industrial space across Wake, Durham, Johnston, and adjacent counties.
For investors, industrial's attraction is the combination of strong occupancy, rising rents, relatively low management intensity, and a tenant base that includes creditworthy national companies alongside smaller regional operators. Modern industrial (built in the last 10-15 years with clear heights of 28 feet or more, dock-high loading, and adequate truck court depth) is the most sought-after product and commands the tightest cap rates.
Older industrial with lower clear heights and limited truck access is still functional but trades at wider cap rates and faces more competition from newer product.
Cap rates for stabilized Triangle industrial run approximately 5.5-7.0% in 2026 depending on building age, location, and tenant quality. The tightest cap rates are for modern, well-located product with long-term leases from national tenants.
Not sure where your capital fits in this market?
Jon Tennant works with commercial investors across all three asset classes in the Triangle. Get a straight read on your specific situation.
Start a ConversationTriangle commercial real estate by asset class, 2026.
| Factor | Retail | Office | Industrial |
|---|---|---|---|
| 2026 Triangle vacancy | ~6-7% | Varies widely by submarket | Near historic lows |
| Typical cap rate range | 6.0-7.5% | 7.0-8.5% | 5.5-7.0% |
| Management intensity | Moderate | Moderate to high | Low to moderate |
| Tenant improvement costs | High | High | Moderate |
| Income stability | Good with NNN tenants | Variable | Strong |
| Market trajectory | Stable to positive | Mixed | Positive |
| Best opportunity type | NNN with credit tenants; necessity retail | Medical office; value-add repositioning | Modern distribution; flex |
There is no universal answer, but here is a practical framework.
Single-tenant NNN retail with a national credit tenant is the simplest structure. You collect rent, pay property taxes (sometimes), and the tenant handles the rest. The tradeoff is lower yield and significant rollover risk when the lease expires.
Value-add office or retail in the Triangle can generate strong returns if you buy right and execute the repositioning. This requires more expertise and more capital but the spread can justify it.
Industrial and flex in the Triangle's growth corridors offers the best combination of occupancy, rent growth trajectory, and demand durability. The entry cap rates are tighter, meaning you pay more per dollar of income, but the income itself is more defensible.
At Jon Tennant Real Estate and Business Brokerage, we work with commercial investors across all three asset classes in the Triangle. Reach out for a conversation about where your capital fits best in this market.
Commercial Real Estate
NOI, cap rate, cash on cash return, lease structure, and stress testing — the seven-step analytical framework.
Commercial Real Estate
The formula, where Triangle commercial real estate is trading in 2026 by property type, and how financing changes the picture.
Commercial Real Estate
Property types, cap rate valuation, due diligence, and SBA 504 and commercial financing for first-time buyers.
Whether you are buying your first investment property or repositioning an existing one, Jon Tennant can give you a straight read on the Triangle market.
Contact Now