October 30, 2026 Jon Tennant 9 min read
The Short Version
A PID — Public Improvement District — is a special annual charge on your property tax bill that pays for the roads, utilities, and infrastructure built to serve your neighborhood. It is usually collected in your monthly escrow payment, it typically adds $50–$400+ per month, and it often runs 20–30 years. It transfers to the next owner when you sell.
If you are shopping for new construction in the Triangle and you have seen references to a PID, a special assessment district, or an infrastructure financing charge on the disclosure documents, you are not alone in wondering what it means. These mechanisms are increasingly common in new development communities across Wake, Johnston, and Chatham Counties — and if you do not understand them before you close, you may be surprised by a payment that was never clearly explained to you. Here is what you need to know.
PID stands for Public Improvement District. It is a financing mechanism that allows a developer to fund the cost of infrastructure — roads, utilities, stormwater systems, parks, and similar improvements — by placing a special assessment on the properties within the district. Instead of the developer paying for infrastructure upfront out of pocket, the cost is effectively spread across the homebuyers through an additional annual charge on their property tax bill.
In North Carolina, PIDs and similar mechanisms go by a few different names depending on how they are structured. You may see them called:
The mechanics vary slightly, but the core concept is the same: you as the homebuyer are paying a share of the cost of building the infrastructure that serves your community, in addition to your regular county property taxes.
The special assessment is typically billed annually as part of your property tax statement, and most mortgage servicers will collect it as part of your monthly escrow payment alongside your regular property taxes and homeowner's insurance.
The amounts vary significantly by community and by the specific infrastructure being financed. In some Triangle new construction communities, the special assessment adds $50–$100 per month to your escrow payment. In communities with larger infrastructure build-outs, the assessment can be $200–$400 per month or more, which is a meaningful addition to your total housing cost.
$50–$100
per month in many Triangle new construction communities
$200–$400+
per month where the infrastructure build-out is larger
20–30 yrs
typical bond term for infrastructure-related assessments
This is not a short-term charge. Special assessments tied to infrastructure financing can run for 20–30 years depending on the bond terms. You are not paying it off in a few years — it is part of the ongoing cost of owning in that community for a long time, and it typically does not go away when you sell, as it transfers with the property to the new owner.
From a developer's perspective, PIDs and special assessments solve a capital problem. Building the roads, utilities, and infrastructure for a large new community requires enormous upfront investment — investment that the developer would otherwise have to finance at development-stage interest rates. By using a PID structure, the developer can bring the infrastructure online without bearing the full upfront cost, which allows them to price homes more competitively at launch even though the long-term cost is ultimately borne by homeowners through the assessment.
For local governments, these structures allow new development communities to fund their own infrastructure without placing the burden on existing taxpayers who do not benefit from the new development. They are a popular tool in rapidly growing counties like Johnston, Chatham, and the outer edges of Wake County.
If you are buying new construction in the Triangle, here are the questions you must ask before you sign:
Is there a PID, special assessment, or infrastructure financing charge on this property?
Ask directly and in writing. Builders are required to disclose these, but the disclosure is sometimes buried in documents that buyers do not fully read.
What is the current annual assessment amount?
Get the specific dollar figure, not just a range.
How long does the assessment run?
Understand the timeline. A 20-year assessment that adds $200/month to your payment is $48,000 in additional cost over its life — money that does not build equity.
Does the assessment transfer to a new buyer when I sell?
In most cases yes. This is important for your own exit planning and for future buyers who will need to factor it into their purchase decision.
Is the assessment included in the payment estimate my builder or lender showed me?
Many buyers are shown a monthly payment estimate during the sales process that does not include the special assessment. Confirm that the escrow estimate accounts for the full tax burden including the assessment.
Does the assessment affect my ability to qualify for a mortgage?
Lenders include property taxes and assessments in the total housing expense ratio used to qualify you. A higher total property tax burden, including the assessment, can affect how much loan you qualify for.
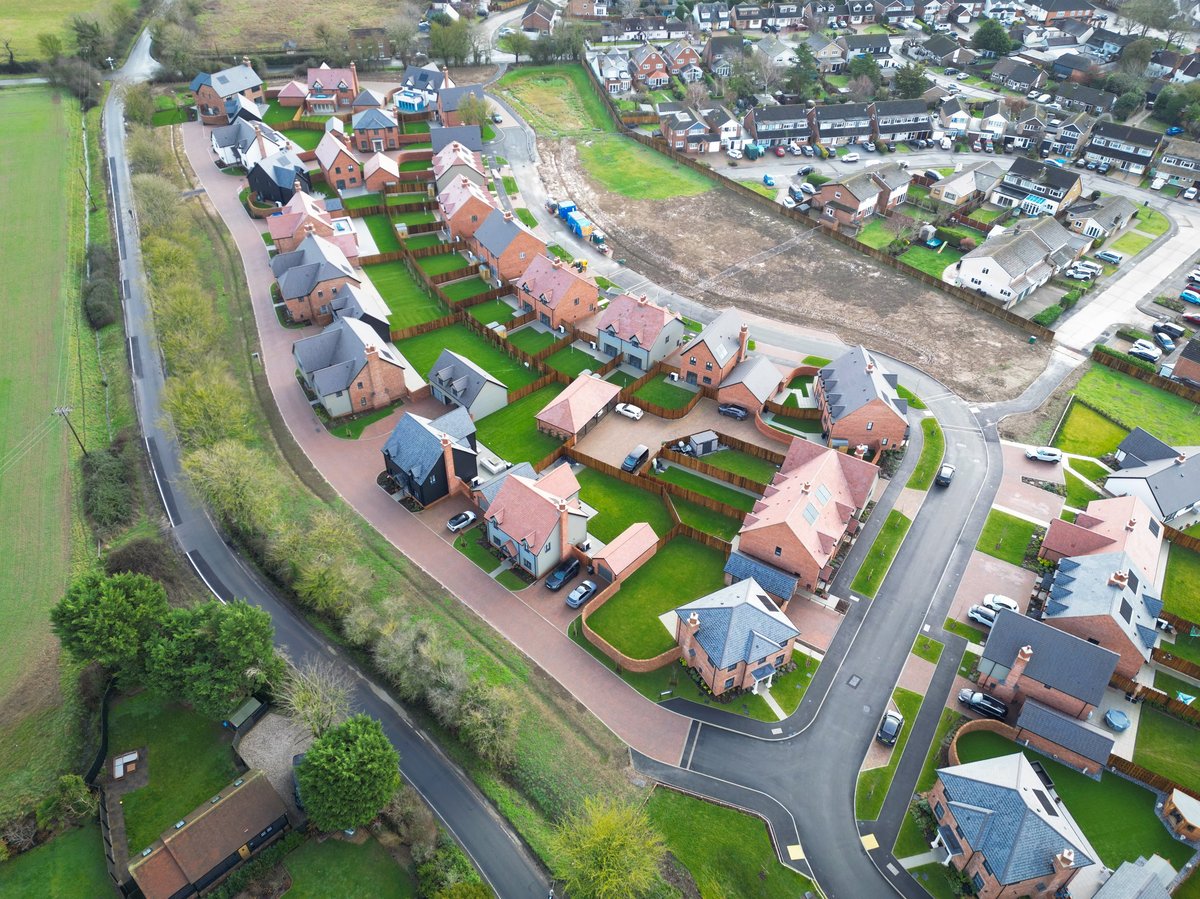
Large master-planned communities and new development areas in Johnston County, eastern Wake County, and Chatham County are the most likely places to encounter PID or special assessment structures. Chatham Park in Pittsboro, some new communities along the I-540 Western Wake corridor, and developments in the Clayton-Garner-Fuquay area have used or are using these financing mechanisms.
This is not universal — many new construction communities do not have PIDs. But in the Triangle's fastest-growing corridors where significant new infrastructure is being built, it is common enough that every new construction buyer should ask the question explicitly.
When you are evaluating a new construction home with a special assessment, add the monthly assessment amount to your total housing cost calculation before you compare it to other options. A home with a $250/month special assessment at a $400,000 purchase price has a higher true monthly cost than a resale home at $425,000 with no assessment. Do the full math before you make a decision based on the base purchase price alone.
At Jon Tennant Real Estate and Business Brokerage, we work with new construction buyers across the Triangle and make sure you understand every component of your total cost before you close. Reach out for a conversation.