One of the most consequential real estate decisions a business owner makes is whether to lease or buy their commercial space. Both paths have real advantages and real trade-offs, and the right answer depends heavily on your business stage, your capital position, and your long-term plans. Here is a straightforward breakdown for business owners in the Triangle who are working through this decision.
Flexibility. Leasing preserves your options. If your business grows faster than expected, you can move to a larger space when your lease expires. If the market shifts or your business model changes, you are not tied to a building. For businesses in early growth stages or industries with significant volatility, that flexibility has real value.
Lower upfront capital requirement. Buying commercial real estate typically requires a 20% to 25% down payment plus closing costs. On a $600,000 building, that is $120,000 to $150,000 in cash out the door before you turn a key. Leasing requires a security deposit and first and last month's rent, freeing that capital for operations, inventory, equipment, or growth.
Predictable cash flow planning. A fixed lease payment is easier to forecast than ownership costs, which include mortgage payments, property taxes, insurance, maintenance, and unexpected capital expenses. For business owners who are managing tight cash flow, the predictability of a lease is a genuine operational advantage.
Access to better locations. Premium locations in high-traffic commercial corridors — downtown Raleigh, North Hills, South Square in Durham, or near RTP — are often unavailable for purchase because owners hold them as long-term investment assets. Leasing gives you access to locations you could not afford or could not acquire.
Building equity rather than paying a landlord. Every mortgage payment builds equity in an asset you own. Every lease payment is gone. Over a 10 to 20-year horizon, owning your commercial space is almost always significantly more wealth-building than leasing comparable space.
Stability and control. When you own your building, you control it. No landlord can raise your rent at renewal, refuse to renew your lease, or sell the property to a developer who wants you out. For businesses where location is central to their brand and customer base, this protection has significant value.
Real estate as a second business. Many successful small business owners build meaningful wealth not just from their operating business but from the commercial real estate they accumulate over time. A business owner who buys their building, operates for 15 years, and then sells both the business and the real estate separately has created two exit assets.
Tax advantages. Commercial real estate ownership comes with depreciation deductions, mortgage interest deductions, and the potential for a 1031 exchange when you sell, which defers capital gains taxes. These benefits are not available to tenants.
Appreciation in the Triangle market. Commercial real estate in the Raleigh-Durham market has appreciated meaningfully over the last decade alongside residential values. Buying commercial space in a growing corridor like the southwest Wake County market, the Durham innovation district, or the RTP periphery puts you in front of that appreciation curve.
For business owners who want to buy their commercial space, the SBA 504 loan program is specifically designed for this purpose. It allows eligible business owners to purchase owner-occupied commercial real estate with as little as 10% down. The structure typically involves a conventional first mortgage covering 50% of the purchase price, an SBA-backed second covering 40%, and a 10% down payment from the buyer.
SBA 504 loans come with long terms (typically 20 to 25 years for real estate) and fixed rates on the SBA portion, which provides payment certainty. For established businesses with at least two years of operating history and sufficient cash flow, the 504 is one of the most powerful commercial real estate financing tools available.
SBA 504 Structure at a Glance
50% conventional first mortgage · 40% SBA-backed second · 10% buyer down payment. Terms up to 25 years for real estate with fixed rates on the SBA portion.
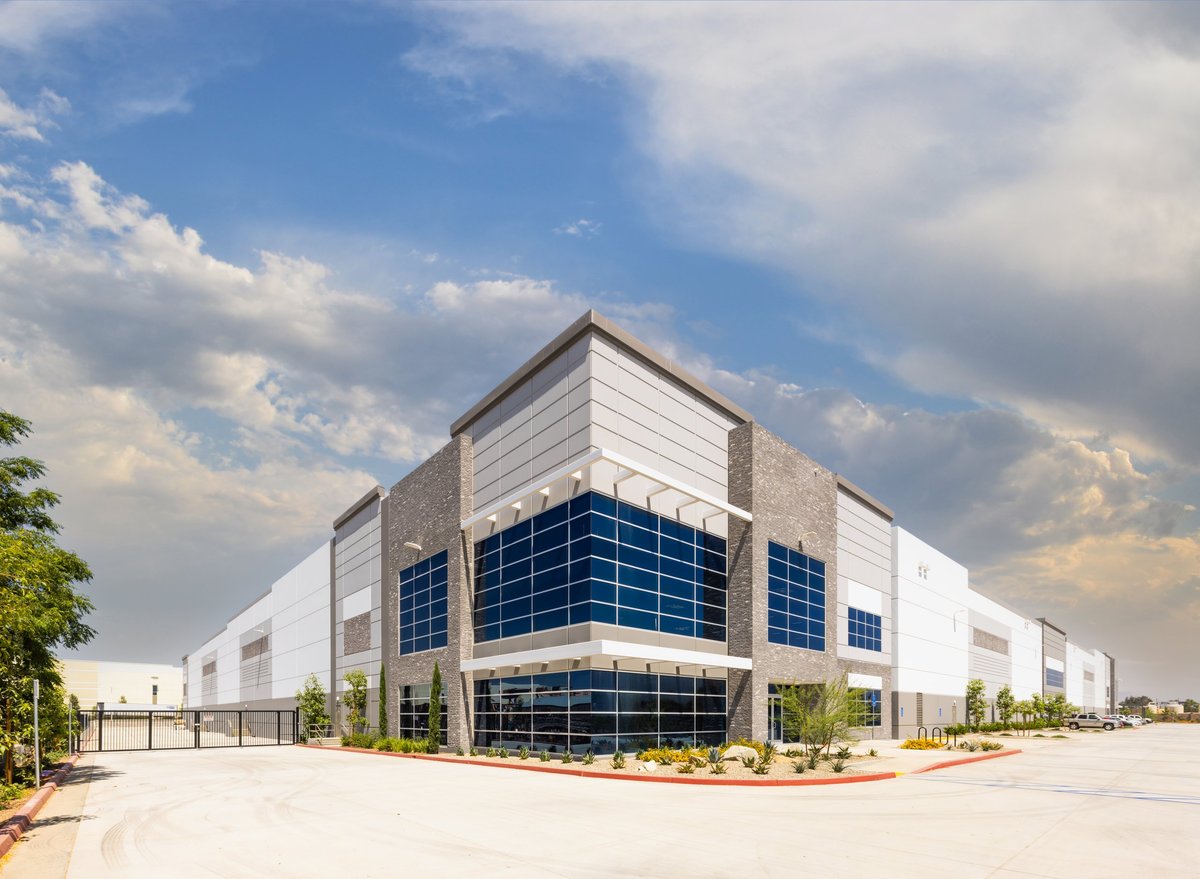
The Triangle commercial market in 2026 is active, particularly in industrial and flex space, which is exactly the category that most owner-occupant buyers are targeting. Availability of quality small-bay industrial and office-warehouse properties in Wake and Durham County is tighter than it was two to three years ago, and prices have reflected that demand.
For business owners considering a purchase, acting before the market tightens further has logic behind it. For those leasing, negotiating longer initial lease terms with renewal options and caps on rent escalation provides meaningful protection in a market where landlords have pricing leverage.
At Jon Tennant Real Estate and Business Brokerage, we work with business owners across Wake and Durham County on both commercial leasing and commercial purchase transactions. Reach out for a conversation about what makes sense for your specific situation.
Leasing vs. buying commercial space in the Triangle
Whether you are weighing a lease or considering an owner-occupant purchase, we work with business owners across Wake and Durham County on both sides of the decision.